
John Hancock | May 2022
Repriced Protection Survivorship IUL. Review the protection SIUL producer guide and Barclays flyer.
Repriced Protection SUL. Review the protection SUL producer guide.
Repriced Protection Survivorship IUL. Review the protection SIUL producer guide and Barclays flyer.
Repriced Protection SUL. Review the protection SUL producer guide.
“Nothing happens in business until somebody makes a sale!” You, the advisor is that somebody – client advocate, solution provider, and a hero to their clients.’ At First American Underwriters (FAIU), we want to be your first and single point-of-contact. The perfect choice and expert in understanding the unique features and nuances of each of your cases. Our in-house team will find you viable practical solutions. FAIU has access to the best products, industry-leading in-house underwriting, and specialized case management solutions to assist you. We know, every hero needs a strong supporting cast to enable their success especially in the most difficult circumstances. Let us be your helper, ally, sidekick, and trusted guide.
When an advisor presents a case, we explore all available options by pre-underwriting in-house. This includes a review of previous similar cases, a broad market survey through our unique quick quote process, outreach to carrier contacts, engagement with healthcare providers, or submission of a trial application. Once we identify the top carrier(s) willing to compete for your business, we facilitate the case design, presentation, underwriting review, and decision, all while advocating on your client’s behalf. We will help you close the deal by securing the best possible offer for your client. Be confident in knowing FAIU underwriting, case design, and new business management solutions will help position you as a hero to your client and someone they can depend on.
— By Sharon Murray, Underwriting Specialist
SwiftTerm allows advisors to offer clients an end-to-end digital experience that can provide them with coverage in as little as 25 minutes if they qualify. Review the competitive heat chart to assure how Symetra SwiftTerm consistently ranks in the top three for low premium. Read More.
PL Promise Term level premium life insurance has adjusted rates again to be more competitive for all ages within preferred no-nicotine risk classes. Read More.
Do you want to increase your share of the business market? How would you like to uncover solid cross-selling opportunities while positioning yourself as a valuable problem-solver? 3 words: Disability… Buy… Out
The Significance of Disability Buy-Out
Some business owners have a buy-sell agreement in place. It is a widespread practice where the partners or the business owns life insurance on the partner’s lives. If one partner dies, the death clause in the agreement triggers the payment of life insurance proceeds to the deceased partner’s family or estate for their share of the business. The remaining partners absorb the deceased partner’s share of the business.
But what if the partner does not die and instead suffers a permanent injury or illness?
Most people do not know that buy-sell agreements typically carry two clauses: a “death clause” as described above and a “disability clause.” In many cases, advisors sell life insurance to fund the buy-sell agreement’s death clause, but they neglect to fund the disability clause. This is a missed opportunity as the average person is six to seven times more likely to become disabled than they are to die during their normal working years.
When a partner becomes disabled and unable to work for an extended period, the other partners and the business face the same consequences as if the partner were to have died. A disabled partner still owns a share of the business and is entitled to its profits but cannot work to help generate those profits, placing additional stress on the business.
What They Do Not Know Can Hurt Them
Check your clients’ buy-sell agreements and if it does include a disability clause, it may contain language that requires the other partners to buy out the disabled partner after a period. If that is the case, where do they get the money to do so?
One simple solution is to fund the disability clause with a disability buy-out policy for each partner. A disability buy-out policy will compensate the disabled partner in one of three ways:
You Know Who to Target
Your top prospects for a disability buy-out are in your book of business—business owner clients with one or more partners. You may have already sold them life insurance to fund one of the clauses. HAs the other been taken care of?
Straightforward Approach
Ask just two questions to start the conversation:
This helps uncover many new opportunities as we are sure you will find many multi-owner businesses do have a buy-sell agreement, mostly unfunded for disability. Many are outdated and have shortfalls for both life and disability, and some are even incorrectly structured.
The primary reason for asking the first question is so you can ask the second question. Nine out of ten businesses have never addressed the possibility of one partner becoming disabled and unable to work. When you help them understand what the disability clause says and that the odds of a disability are far greater than death in their working years, it creates the opportunity for you to help them resolve this key area as a problem solver. This will help differentiate you by identifying problems they did not know they had and offering a solution and will also open the door to additional opportunities and referrals.
Working with First American Insurance Underwriters, we will help you find a disability buy-out solution tailored for your clients’ needs and circumstances. Reach out to us and we will find the best solution for you and your client.
— By Ed Stone, LTC, DI & Annuity Specialist
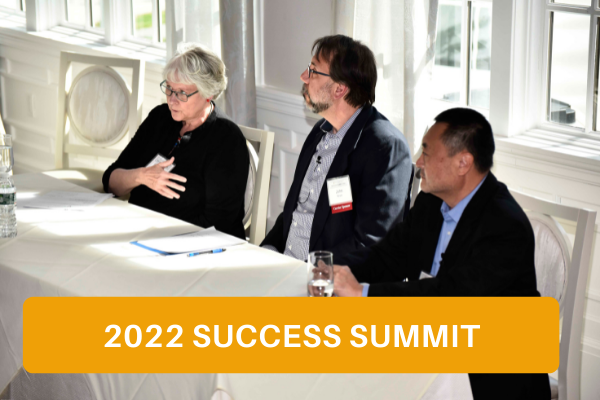
NEEDHAM, MA — May 17, 2022 — First American Insurance Underwriters (FAIU) held its 19th Annual Success Summit on May 11, 2022, at the Pine Brook Country Club in Weston, MA. The event was well-attended with over 100 registered participants and 16 of the top insurance carriers in the U.S.
The half-day event included several moderated sessions: Underwriting, Advanced Market Concepts, and Carrier Spotlights. Companies participating in the Success Summit included AIG, Allianz, Global Atlantic Financial Group, John Hancock, Legal & General America, Lincoln Financial Group, MassMutual, Mutual of Omaha, National Life Group, Nationwide, Pacific Life Insurance Company, Principal Financial Group, Protective Life, Prudential, SBLI, and Symetra. The registered participants also enjoyed networking opportunities throughout the day.
FAIU President Ken Shapiro praised the event as “a tremendous opportunity to bring insurance advisors together with top carriers to advance their knowledge of insurance solutions that will elevate their practices and their stature in front of their clients.”
Available now, subject to state availability, Lincoln WealthPreserve® 2 Survivorship IUL (2022) offers long-term protection, built-in guarantees, and lifelong flexibility. Built for couples who want solid, cost-effective protection for two lives under one policy.
After careful consideration, Lincoln has made the decision to discontinue new sales of Lincoln LifeGuarantee® UL (2019) and Lincoln LifeGuarantee® SUL (2019) (Survivorship UL), which accounted for just 1% of all Lincoln Life sales in 2021. These changes are effective in all states, June 10, 2022. The changes do not impact inforce policyholders. Read More.
Effective Immediately: Rates Have Gone Up!
Informal Process Update
To provide strong service on large/higher premium informal cases as well as your formal applications, we are updating our informal submission guidelines as follows:
• Minimum face amount of $1M on permanent products
• Minimum face amount of $4M on term products
This change in our process will allow us to focus more resources on your larger/higher premium cases and formal applications.
New S&P PRISM Index Now Available!
Persistency Bonus On Premier Variable Universal Life (PVUL) Policies